Short version:
• Luxury residences in Boca Raton almost always require jumbo financing, since prices routinely exceed the county conforming loan limit.
• New construction condos carry additional lender scrutiny around reserve funding and condo project approval.
• Preparing your financial profile early — credit, reserves, and documentation — is the most effective way to streamline the purchase process.
When exploring Boca Raton Residences For Sale, buyers entering the luxury market face a financing landscape that differs significantly from a standard home purchase. Many properties fall well above conforming loan thresholds, making it essential to understand jumbo loan requirements, condo-specific underwriting rules, and how to position your financial profile before making an offer.
Why Jumbo Financing Dominates This Market
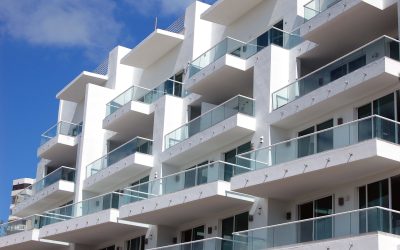
The 2026 conforming loan limit in Palm Beach County is $832,750, and that figure covers the majority of Boca Raton purchase scenarios for standard homes. However, a development like Glass House Boca Raton — a limited collection of 28 residences across 10 floors with delivery in 2026 — starts at $2.5 million, placing virtually every unit far above that threshold.
A jumbo mortgage loan in Boca Raton is one that exceeds the conforming loan limits set by the Federal Housing Finance Agency (FHFA). For most of Florida, the conforming loan limit is $806,500 for a single-family home in 2025. Homes in high-demand areas like Boca Raton often exceed this limit, requiring a jumbo loan to finance the purchase.
To qualify for a jumbo loan, buyers typically need a strong credit score, a low debt-to-income ratio, and proof of stable income and assets. Lenders often require a larger down payment, usually 10 to 20 percent or more. According to the Federal Housing Finance Agency’s conforming loan limit resources, these thresholds are adjusted annually based on national home price movement, so verifying the current limit before applying is always advisable.
Loan Qualification Criteria at a Glance
The table below summarizes the primary financing types relevant to Boca Raton luxury residences and their general requirements:
|
Loan Type |
Typical Down Payment |
Credit Score Minimum |
Best Suited For |
|
Jumbo (Non-Conforming) |
10-20%+ |
700-720+ |
Luxury condos and estates above $832,750 |
|
Conventional (Conforming) |
3-5% |
620+ |
Properties within county loan limit |
|
FHA |
3.5% |
580+ |
Entry-level Boca neighborhoods, select approved condos |
|
Portfolio / Bank Statement |
10-30% |
Varies by lender |
Self-employed or non-W-2 buyers |
Most lenders require a minimum credit score of 680 to 700 for jumbo loans, with the best rates reserved for scores of 740 or higher. Some lenders may approve borrowers with scores as low as 660, but expect higher interest rates and stricter requirements.
Self-employed borrowers may not fit into standard W-2 requirements, but loan programs designed for those situations exist. Options include bank statement loans, asset depletion, and profit-and-loss documentation.
Condo-Specific Underwriting: A Critical Layer
Purchasing a unit in a new luxury condo development adds a layer of underwriting complexity that many buyers underestimate. Lenders do not simply evaluate the borrower — they also evaluate the building itself.
The 2025 reserve rules for conventional condo financing are one of the biggest factors that determine whether a Boca Raton condo can be financed smoothly or becomes a source of frustration and delay. Lenders are looking more closely at building reserves, structural risk, and association budgets, and that extra scrutiny shows up most clearly in coastal markets like Boca Raton.
A condo project can be deemed ineligible for conventional financing when certain red flags appear. These can include extremely low reserve funding, unresolved structural issues, open safety concerns, or major litigation that threatens the financial stability of the association.
For new construction specifically, buyers should confirm with their lender that the project has received — or is on track to receive — condo project approval before signing a purchase contract. A pre-sale percentage requirement and minimum owner-occupancy ratio are common hurdles for new developments.
Pre-Purchase Financial Steps
Getting your financing in order before touring residences protects your negotiating position and prevents delays at contract.
• Check your credit profile. Pull all three bureaus and resolve any errors at least 90 days before applying.
• Quantify your reserves. A credit score of at least 700, a down payment of at least 10 to 20 percent, and cash reserves for 6 to 12 months are needed for most jumbo loans.
• Gather income documentation early. Tax returns, W-2s, or bank statements for the prior two years are standard requirements.
• Obtain a pre-approval letter. In a competitive luxury market, sellers expect documented financing capacity before accepting offers.
• Consult a lender familiar with South Florida condo projects. Property values and loan requirements can vary significantly across Boca Raton, and working with a local mortgage professional means getting a partner who understands Palm Beach County appraisal nuances and insurance requirements.
Frequently Asked Questions
Do all Boca Raton luxury residences require jumbo loans? Not automatically — the loan amount, not the purchase price, determines the loan type. A large down payment can bring the financed amount below the conforming limit, but at price points starting above $2.5 million, most buyers will require jumbo financing regardless.
Can a foreign national purchase a Boca Raton residence with financing? Yes, though options are more limited. Portfolio lenders and private banks typically offer foreign national loan programs, usually requiring 30 to 40 percent down and substantial asset documentation.
How does new construction affect the financing timeline? Closing timelines on new construction are tied to the developer’s delivery schedule. Buyers typically lock their rate closer to the completion date, and lenders may require updated financial documentation if the process extends beyond 60 to 90 days.
What is the role of a condo questionnaire in the approval process? Lenders require a completed condo questionnaire from the homeowners association before approving financing. It captures reserve funding levels, pending litigation, and owner-occupancy ratios — all factors that determine project eligibility.
Financing a luxury residence in Boca Raton is a multi-step process that rewards preparation. Understanding the jumbo loan landscape, condo project approval requirements, and documentation expectations before you enter the market puts you in a far stronger position when the right property becomes available.
For buyers exploring Boca Raton residences for sale in a boutique luxury development, Glass House Boca Raton offers a limited collection of 28 residences in the heart of downtown Boca Raton, combining hypermodern architecture with a full suite of concierge amenities. Connecting with the sales team early gives buyers the lead time needed to align financing with the project’s delivery schedule.